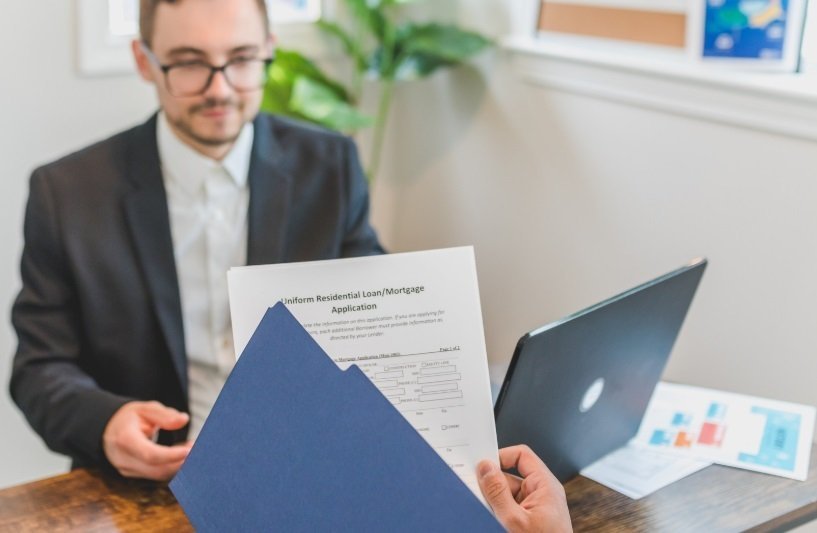
A first-time immigrant homebuyer reviews mortgage documents and alternative credit requirements for ITIN financing.

For many newcomers to the United States, visa holders, and international investors, one question often arises before purchasing a home:

Can you get a mortgage without a Social Security Number?

The answer is yes.

Thanks to the growing popularity of the ITIN Loan market, borrowers who do not have an SSN can still qualify for financing and achieve their homeownership goals in the United States.

As more lenders expand specialized mortgage programs, ITIN financing has become one of the most practical solutions for immigrants and foreign nationals looking to buy property.

What Is an ITIN Loan?

ITIN stands for:

Individual Taxpayer Identification Number

Issued by the IRS, an ITIN is designed for individuals who are required to file taxes in the United States but are not eligible for a Social Security Number.

Many people holding:

  • Work visas
  • Student visas
  • Dependent visas
  • Investment visas

may not have an SSN but can legally obtain an ITIN.

An ITIN mortgage is specifically designed to help these borrowers qualify for home financing.

Why Can Borrowers Without an SSN Qualify for a Mortgage?

Historically, most lenders only approved borrowers with Social Security Numbers.

However, as immigrant populations have grown and housing demand has expanded, lenders recognized that many ITIN holders possess:

  • Stable income
  • Long-term employment
  • Strong tax filing history
  • Significant savings
  • Reliable repayment ability

As a result, a mature ITIN Mortgage Program market has developed across the United States.

Who Should Consider an ITIN Loan?

New Immigrant Families

Recent arrivals often have not yet received an SSN but are already building their lives in the United States.

Work Visa Holders

Borrowers with visas such as:

  • H-1B
  • L-1
  • O-1

may qualify through ITIN-based financing.

Self-Employed Borrowers

Business owners who report taxes using an ITIN can often benefit from specialized lending programs.

Family Visa Holders

Some spouses and dependents may not possess Social Security Numbers but still qualify for mortgage financing.

For these groups, a New Immigrant Home Loan can provide a realistic path to homeownership.

ITIN Loan Qualification Requirements

Although requirements vary among lenders, most programs require:

Valid ITIN Number

Applicants must have an active and valid Individual Taxpayer Identification Number.

Proof of Income

Lenders typically request:

  • Pay stubs
  • Bank statements
  • Tax returns
  • Employment verification

Down Payment

Most lenders require:

  • 10% to 25% down payment

Requirements depend on credit profile, property type, and loan program.

Credit Evaluation

Even without traditional credit history, borrowers may still qualify through alternative credit verification.

Can You Qualify Without a Credit Score?

Many ITIN borrowers also lack traditional U.S. credit scores.

Fortunately, some lenders accept:

Alternative Credit Documentation

Examples include:

  • Rent payment history
  • Utility bills
  • Phone bills
  • Insurance payments

Demonstrating consistent payment behavior can significantly improve approval chances.

This flexibility is one reason the No SSN Mortgage market continues to grow.

How ITIN Loans Differ from Traditional Mortgages

Traditional Mortgage Requirements

Typically include:

  • Social Security Number
  • Credit score
  • Standard income verification
  • Conventional underwriting guidelines

ITIN Loan Requirements

Generally allow:

  • ITIN instead of SSN
  • Alternative credit review
  • Flexible income documentation

However, borrowers should expect interest rates to be somewhat higher than conventional mortgage programs.

A family meets with a mortgage advisor to discuss ITIN Loan options for purchasing a home in the United States without an SSN.

Typical Down Payment Requirements

Down payment requirements often depend on occupancy type.

Primary Residence

Usually requires:

10%–20% down

Investment Property

Typically requires:

20%–30% down

Higher-Risk Profiles

Borrowers with limited credit history may need larger down payments.

A higher down payment often improves approval odds and may help secure better loan terms.

What Types of Properties Can Be Purchased?

Most lenders allow financing for:

Single-Family Homes

The most common property type.

Condominiums

Eligible condo projects may qualify.

Multi-Family Properties

Including:

  • Duplexes
  • Triplexes
  • Fourplexes

Investment Properties

Certain programs support real estate investment purchases as well.

Because of this flexibility, ITIN financing appeals to both homeowners and investors.

How to Improve ITIN Loan Approval Chances

Maintain Stable Income

Lenders prioritize consistent earnings.

Increase Your Down Payment

Reducing lender risk can strengthen your application.

Build Credit History

Establishing payment records helps improve financing options.

Document Assets Clearly

Lenders often review the source of funds used for down payments.

Obtain Mortgage Pre-Approval

Pre-approval can strengthen your position when making offers on properties.

ITIN Loans vs. Non-QM Loans

Borrowers frequently encounter both ITIN and Non-QM financing options.

While they can overlap, they solve different challenges.

ITIN Loans

Primarily address borrower identification and immigration-related issues.

Non-QM Loans

Focus on alternative income verification methods.

Some lenders combine both features by offering:

  • ITIN eligibility
  • Bank statement underwriting
  • Alternative income documentation

This combination can be particularly attractive for immigrants and self-employed borrowers.

2026 ITIN Mortgage Market Trends

The ITIN lending market continues to expand rapidly.

Industry trends suggest:

  • More lenders entering the market
  • Increased rate competition
  • Lower entry barriers
  • More specialized loan products
  • Faster digital approval systems

For immigrant communities and international buyers, these developments create additional opportunities for homeownership.

What Should Borrowers Consider Before Applying?

Before submitting an application, evaluate:

  • Credit-building strategies
  • Down payment readiness
  • Income stability
  • Debt-to-income ratio
  • Lender experience with ITIN programs

Working with an experienced mortgage professional can significantly improve your chances of approval.

Conclusion

For immigrants and international buyers without a Social Security Number, the ITIN Loan has become an important gateway into the U.S. housing market.

Although qualification requirements differ from traditional mortgages, borrowers with a valid ITIN, stable income, and sufficient down payment often have excellent opportunities to obtain financing.

As the mortgage industry continues evolving, more borrowers are successfully achieving homeownership through ITIN mortgage programs. Whether you are a first-time buyer, self-employed entrepreneur, visa holder, or new immigrant, understanding these financing options can help turn your American homeownership goals into reality.

无论您是首次购房、自雇人士,还是外籍投资人,我们都能为您推荐最适合的贷款产品,帮您轻松跨出安家第一步。