

FHA loan programs have become a practical solution for buyers who struggle to accumulate a large down payment. Instead of requiring the traditional 20% upfront, borrowers may qualify with as little as 3.5%, and in some cases combine assistance programs to approach a 0 down payment mortgage structure. These options significantly lower the barrier to homeownership, particularly for individuals with limited savings but stable income.
What Is an FHA Loan
An FHA loan is backed by the Federal Housing Administration and is designed to support borrowers with moderate credit scores or limited financial reserves. Compared to conventional financing, underwriting standards are more flexible, especially regarding credit history and initial cash requirements. Because of this structure, it is frequently recommended in any first-time homebuyer guide.
Under standard guidelines, borrowers meeting minimum credit thresholds may qualify for a 3.5% down payment. Those with stronger profiles may secure improved rate terms. This flexibility makes the program one of the most accessible entry points into the housing market.
How 0–5% Down Payment Programs Work
Many buyers assume substantial cash savings are mandatory to purchase a home. In reality, low down payment home loan programs across the United States include state grants, community lending initiatives, and targeted assistance programs.
A 0 down payment mortgage arrangement typically combines an FHA loan application with down payment assistance grants or secondary support programs. Eligibility may depend on income caps, geographic location, or buyer status. For households with consistent earnings but limited liquidity, these structures can accelerate entry into real estate ownership.
FHA Loan Application Process
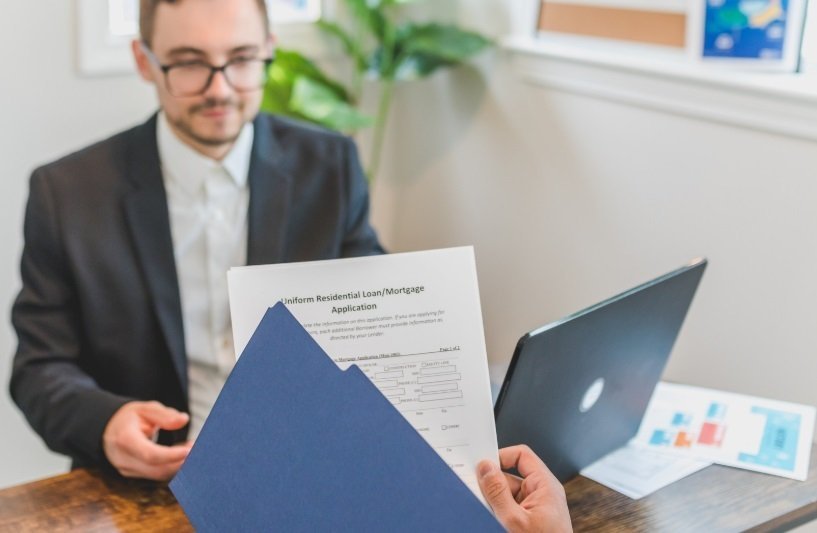
The FHA loan application process generally involves four stages: pre-approval, formal submission, property appraisal, and final underwriting approval. During preparation, borrowers organize income documentation, bank statements, and credit records.
Pre-approval letters are especially important in competitive markets, signaling to sellers that financing capacity has been verified. The lender will also conduct an appraisal to confirm the property meets value and safety standards. When documentation is complete, approvals commonly take 30 to 45 days.
Credit and Income Requirements
Although FHA standards are more flexible, approval still depends on consistent income and responsible debt management. Lenders review the debt-to-income ratio to ensure long-term repayment stability.
Self-employed applicants may provide two years of tax returns or verified bank statements to demonstrate earnings continuity. Managing credit utilization effectively can further improve qualification terms.
Costs and Insurance Considerations
Borrowers should understand that FHA loans require mortgage insurance premiums (MIP). While this increases monthly obligations, it enables lower upfront capital requirements. Over time, some homeowners consider refinancing strategies to reduce insurance expenses if equity and credit profiles improve.
Does Low Down Payment Mean Higher Risk
Lower down payment structures do not automatically translate into higher financial risk. Budget planning remains the critical factor. Buyers must account for mortgage payments, property taxes, insurance, and maintenance costs.
For many households, homeownership represents both residential stability and long-term asset growth. Entering the market through a structured FHA loan can serve as a strategic financial step rather than a liability.
How to Decide if an FHA Loan Is Right for You
If your credit profile is acceptable but savings are limited, an FHA loan may provide the ideal balance between accessibility and affordability. Buyers with strong financial reserves and excellent credit may compare conventional alternatives to evaluate total lifetime cost.
In a shifting real estate environment, preparation is essential. Understanding approval criteria, organizing documentation, and evaluating low down payment home loan options position buyers for confident decision-making. With informed planning, sustainable homeownership becomes an achievable goal rather than a distant aspiration.